Joe Nocera Quotes
Banks always want their capital requirements to be as low as possible, so they can take more risks, which can enable them to make more money – and reap bigger bonuses for executives.
Actually, even with higher capital requirements, the banks could take more risk but then they would have to risk their own money rather than their depositors’ funds. The depositors funds are at risk but if the risk pays off, only the bank and their executives profit. The depositors get nothing. If the bank loses their risky gamble, the major loss will be covered by the Government via a bail out and/or Federal Deposit Insurance money that protects most depositors. For the Banks, its “heads we win; tails the government loses”.
Joe Nocera, Financial Journalist, Columnist, and Writer, Explanation of the basic reason for the Meltdown of 2008 and the Great Recession that followed, “Sheila Bair’s Bank Shot”, New York Times Magazine, July 10, 2011
Sourced by: Eigen's Political and Historical Quotations


4 years after the Great Recession where major banks of America needed government bailouts to prevent failure the Administration and Federal Reserve board wanted to increase the capital requirements to increase the safety of the Banks. Essentially the banks would speculate and gamble with depositors’ money. If their investment paid off, there were large profits and bonuses for the executives. If it did not, they ran out of capital as they had very little of their own at risk. The government bailed them out and the executives got their bonuses anyway. The efforts to make the banks speculate with more of their own money were strongly opposed by the banks and bank executives.

U. S. Treasury Secretary Larry Summers called Rajan a “Luddite” for this view, but what Rajan observed and predicted was exactly what happened in the Meltdown of 2008 which led to the Great Recession. Rajan was one of the few economists to call this right. Several, invested their own money assuming a crash and made billions. Most, like Summers and the Federal Reserve Chairmen in retrospect admitted that they missed the signs and didn’t connect the dots. See {637168}, {637987}, and {620038}

Born thought that her agency was responsible for regulating the new esoteric financial products—derivatives including credit default swaps—for otherwise there would be no regulation at all of financial products that could dwarf the stock and bond market. Summers persuaded her to back off. When the Meltdown of 2008 hit, the huge derivative exposure of the large banks and some insurance companies was so great that it was one of the major causes for the meltdown of the entire banking system. Summers, normally a great economist not only called this one wrong, but later, along with most other government and private economists ignored a very explicit warning—See {637168}, {637986}, and {620038}.


The Meltdown of 2008 and Great Recession that it caused

He was referring to Fannie Mae, the government-created. private mortage guarantee company. It was heavily regulated, and in general it met the regulatory requirements. However, the requirements were insufficient, and in the 2008 Meltdown and the Great Recession that followed, Fannie Mae itself was in such bad financial condition, that the Federal Government had bail them out or have the entire home mortgage industry fall apart.


by disclosing elements of the savings and loan scandal.


The result was regulation of the banks and the creation of the SEC to regulate the stock market, However, over the years, the regulations were not able to keep up with the sophisticated development of new forms of investments and financial instruments and the financial industry were able to speculate with other people’s money in ways that FDR and his reformers never imagined. Finally, even the regulation that did exist was weakened by the policies of the George W. Bush administration and the combination brought about the Great Recession of 2008 where the profits from excess speculation were privatized and the losses, socialized with the taxpayer and the American worker bearing the brunt while most of the speculators were bailed out and made more money than ever. The Obama administration tried to reform the situation, but was unable to put an end to the legal speculation with other people’s money or of having institutions that were “too big to fail.”

The Treasure Officials had a reason for bailing out the bondholders. They were afraid that if bank bondholders and owners took big losses at that time, it would “spook” the financial markets and cause even worse panics than then existed. The political pressure would be to bail out the financial institutions which would have lost much more money after the “spooking”. So it was, they argued, less cost to the taxpayer to bail out the bondholders at the beginning and save the bailout costs later. Some argued that there was no reason to bail out the richest people in America if they lose a lot of money so it is not an issue of bail out now or later. History shoed that the financial leaders did have the clout to force the government to bail them out however. There are some who wanted to have a showdown with the wealth banks and other financial institutions and let them go bankrupt and then the economy would right itself. No one really knows for sure which is why Economics is called the “dismal science”—See {596873}.

Banks often lie. The system encourages them to do so. In a crisis, if a bank honestly says that it is not sure that it has enough cash and other liquid assets, others will not lend it any more money and depositors will rush to withdraw their money, thereby almost insuring a failure. The bank that lies, might weather the storm and survive.


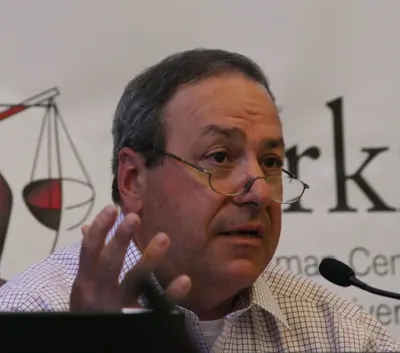
Joseph Nocera is an American business journalist and author. He writes about sports at The New York Times where he previously wrote about business and was a columnist for the newspaper's Op-Ed page. Nocera is also a business commentator for NPR’s Weekend Edition and, as of January 2017, for Bloomberg View.
